in headline earnings
US dollar PGM basket prices at Two Rivers and Modikwa mines increased by 68% and 65%, respectively
Bokoni development project approved
Unit costs remained under pressure due to lower production volumes and above-inflation increases in costs
Nkomati restart approved
Acting chief executive – ARM Platinum
US dollar PGM prices increased significantly in F2026 compared to prices achieved in F2025. The average rand per 6E kilogramme basket price improved as follows:
Average US dollar metal prices
| Unit | F2026 | F2025 | % change |
||
| Platinum | US$/oz | 1 796 | 993 | 81 | |
|---|---|---|---|---|---|
| Palladium | US$/oz | 1 442 | 983 | 47 | |
| Rhodium | US$/oz | 8 319 | 4 767 | 75 | |
| Nickel | US$/t | 16 347 | 15 746 | 4 | |
| Copper | US$/t | 11 767 | 9 311 | 26 | |
| Cobalt | US$/lb | 22 | 12 | 83 | |
| UG2 chrome concentrate (CIF)* | US$/t | 279 | 262 | 7 |
* CIF: cost, insurance and freight.
Average rand metal prices
| Unit | F2026 | F2025 | % change |
||
| Average exchange rate | ZAR/US$ | 16.88 | 18.15 | (7) | |
|---|---|---|---|---|---|
| Platinum | ZAR/oz | 30 289 | 18 026 | 68 | |
| Palladium | ZAR/oz | 24 309 | 17 851 | 36 | |
| Rhodium | ZAR/oz | 140 268 | 86 526 | 62 | |
| Nickel | ZAR/t | 275 642 | 285 827 | (4) | |
| Copper | ZAR/t | 198 403 | 169 020 | 17 | |
| Cobalt | ZAR/lb | 376 | 213 | 77 | |
| UG2 chrome concentrate (CIF)* | ZAR/t | 4 704 | 4 747 | (1) |
* CIF: cost, insurance and freight.
F2025 in the inner circle
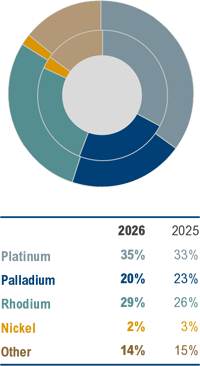
ARM Platinum headline earnings increased by more than 200% to R1 345 million (F2025: R1 288 million loss), mainly due to strengthening US dollar PGM basket prices:
Two Rivers Mine
Volumes
Tonnes milled were 1% lower compared to F2025. The overall grade declined to 3.00g/t (F2025: 3.03g/t). PGM production volumes declined by 1% to 286 590 6E PGM ounces (F2025: 288 502 6E PGM ounces), due to productivity being impacted by sympathetic geological structures affecting mining flexibility.
Unit costs
The unit cash cost per 6E PGM ounce increased by 13% to R18 487 (F2025: R16 431), mainly driven by inflation and above-inflation increases in diesel, explosives, consumables and labour costs. Labour cost increases were 2% above inflation, reflecting increased bonus payments on improved profitability. The impact of the above-inflationary cost increases on unit costs was exacerbated by a reduction in PGM ounces produced and increased mining development costs.
Modikwa Mine
Volumes
Tonnes milled improved by 1% to 2.45 million tonnes (F2025: 2.43 million tonnes). While underground UG2 development is currently being ramped up, face-length availability remained constrained during the year as a result of previous development delays.
As a transitional measure to offset these historical shortfalls, open-pit mining was introduced in F2025 to maintain plant feed. PGM production decreased by 3% to 273 671 6E PGM ounces (F2025: 281 638 6E PGM ounces), reflecting temporary plant recovery impacts caused by blending open-pit ore into the feed mix.
Unit costs
Unit cash costs were up 8% to R20 909 per 6E PGM ounce (F2025: R19 399 per 6E PGM ounce), largely due to the above-inflationary increase in diesel costs and a 3% reduction in PGM ounce production.
Bokoni Mine
Update
The board approved the development of the Bokoni 180ktpm project following the completion of the DFS in June 2026.
The project is expected to deliver an NPV of R5.9 billion, based on the future nominal capital expenditure of R15.2 billion and a nominal post-tax discount rate of 18.47%. The expected IRR on the future cash flows is 28.0%, with a payback period of 6.3 years.
First production from the refurbished 60ktpm concentrator is scheduled for 1H F2028, followed by commissioning of the new 120ktpm concentrator in 2H F2030, with steady-state production of 350 000 to 400 000 6E PGM ounces per annum. The phased, brownfield-led approach materially derisks execution and positions Bokoni below the 50th percentile of the global PGM cost curve, reinforcing ARM's positioning as a globally competitive, low-cost PGM producer.
For further details, refer to the SENS announcement released on 23 July 2026 and the investor presentation conference call held on 31 July 2026, available on the ARM website www.arm.co.za.
The strategic development focus for F2026 was to establish the critical infrastructure and mining access required to support sustainable production growth. Key activities included advancing the 02 level east, 03 level east and west footwall drives. Development also progressed towards the planned ventilation shafts. In addition, the conveyor and material declines were extended to 04 level. These initiatives were aimed at improving mine access, enhancing ventilation capacity and creating the platform necessary for future production expansion.
A total of 2 684 metres of off-reef development was completed during the period, inclusive of the main decline systems. In addition, 377 metres of on-reef development was achieved, with 80% of this work executed within the final five months of the financial year, following the successful recruitment and deployment of dedicated on-reef development crews. This accelerated delivery reflects the effectiveness of the resourcing strategy and demonstrates a strong commitment to building mining flexibility and unlocking future ore reserves.
The tunnel-boring machine (TBM) infrastructure was successfully constructed, fully commissioned and handed over ahead of schedule in November 2025. Once the TBM turned onto strike, ground conditions improved and development reached 279 metres at the end of June 2026.
Nkomati Mine
Nkomati has been on care and maintenance since F2021.
After ARM acquired full ownership of Nkomati Nickel Mine in July 2025, management streamlined governance, accelerated decision-making and advanced a clear restart pathway for the asset. Nkomati remained a key strategic focus for ARM during the year, as the group moved from preserving the asset under care and maintenance to positioning it for value creation.
In July 2026, the ARM board approved the recommencement of open-pit mining operations and nickel concentrate production at Nkomati, following completion of the DFS and the conclusion of the nickel concentrate offtake agreement with Boliden Commercial AB (Boliden). The offtake agreement has not yet become unconditional and remains subject to the fulfilment or waiver, as applicable, of the remaining conditions precedent relating to the establishment of acceptable loading port access.
The restart of Nkomati's open-pit nickel mining operations represents a low-risk, immediately actionable development opportunity. The project leverages Nkomati's existing mining and processing infrastructure and is underpinned by a large polymetallic resource with a secured nickel concentrate offtake arrangement, which re-establishes South Africa's only primary nickel producer.
Management's near-term focus is on execution readiness, including finalising the remaining offtake agreement conditions precedent, preparing the open-pit and processing operations for restart, maintaining cost discipline and advancing the chrome recovery and optimisation opportunities that could further enhance the long-term economics of the asset.
For further detail, refer to the SENS announcement released on 23 July 2026 and the investor presentation conference call held on 31 July 2026, available on the ARM website www.arm.co.za.
At 30 June 2026, the estimated undiscounted rehabilitation costs were determined to be R2 191 million (30 June 2025: R2 301 million), excluding VAT. The discounted rehabilitation costs were determined to be R1 641 million at 30 June 2026 (30 June 2025: R2 123 million).
At 30 June 2026, R381 million in cash and financial assets was available to fund rehabilitation obligations for Nkomati Mine.
Nkomati Mine's estimated rehabilitation costs continue to be reassessed as engineering designs evolve and new information becomes available.
Total attributable capital expenditure for ARM Platinum increased by 39% to R2 759 million for the period (F2025: R1 978 million). The increase was primarily driven by expenditure at Bokoni, where R718 million was spent on mine development.
| R million | F2026 | F2025 | |
| ARM Platinum | |||
| Modikwa Mine | 622 | 222 | |
| Two Rivers Mine | 1 017 | 1 193 | |
| Bokoni Mine | 1 091 | 563 | |
| Nkomati Mine | 29 | – | |
| ARM Platinum | 2 759 | 1 978 |
Two Rivers Mine
Capital expenditure decreased by 15% to R1 017 million (F2025: R1 193 million). Of the total, R524 million related to deepening declines at the Main and North shafts, along with electrical and mechanical installations. A further R184 million related to expenditure on fleet replacement and rebuilds. F2025 included R267 million of capital expenditure relating to the Merensky project prior to being placed on care and maintenance.
Merensky project
A decision was taken to place the Merensky project on care and maintenance in July 2024. Prior to this transition, key capital milestones were successfully completed, including constructing the Merensky concentrator plant and establishing the first two mining levels.
In October 2025, decline development selectively resumed on the Merensky on-reef decline shaft to establish additional dip levels. This targeted development enhances operational readiness, positioning the asset for an accelerated production ramp-up.
The immediate focus at Two Rivers is to fill the capacity of the UG2 concentrator plant, with two Merensky stoping crews deployed. The Merensky ore produced will be processed in the UG2 concentrator plant.
The development pathway for the Merensky project is expected to be submitted for board consideration in F2027. We will engage the market once an investment decision has been reached. This approach reflects our focus on disciplined capital allocation to mitigate execution risk and maximise project returns. The long-term fundamentals for the Merensky project remain accretive.
Modikwa Mine
Capital expenditure at Modikwa Mine (100% basis) increased by 180% to R1 244 million (F2025: R444 million). Of the total, R100 million related to capital development, R294 million to fleet refurbishment and critical spares, R273 million to infrastructure capital expenditure and R250 million to waste stripping at the open-pit.
North shaft project
The downcast ventilation project was initiated to provide additional ventilation below level 10. Safe holing was completed in June 2026 and the thin concrete layer application process at the end of August 2026.
South 2 shaft project
The underground-to-surface conveyor belt that connects South 2 infrastructure to South 1 shaft has been re-baselined due to operational complexities and site preparation delays. Construction is progressing and the forecast completion date is October 2026. This delay will not negatively impact production.
Open-pit project
Modikwa began open-pit mining in 2024, with initial trial pits developed in the South 1 area, while permitting and access were being finalised for the larger South 3 pit. Mining at the South 3 open-pit, located on the Winterveld farm, began in the second half of 2025. The project is currently producing 35 000 tonnes per month.
Merensky project
The Merensky mining project is progressing well, with volumes at 50 000 tonnes per month.
Bokoni Mine
Of the R1 091 million spent at Bokoni, R718 million related to mine development and R193 million to the TBM.